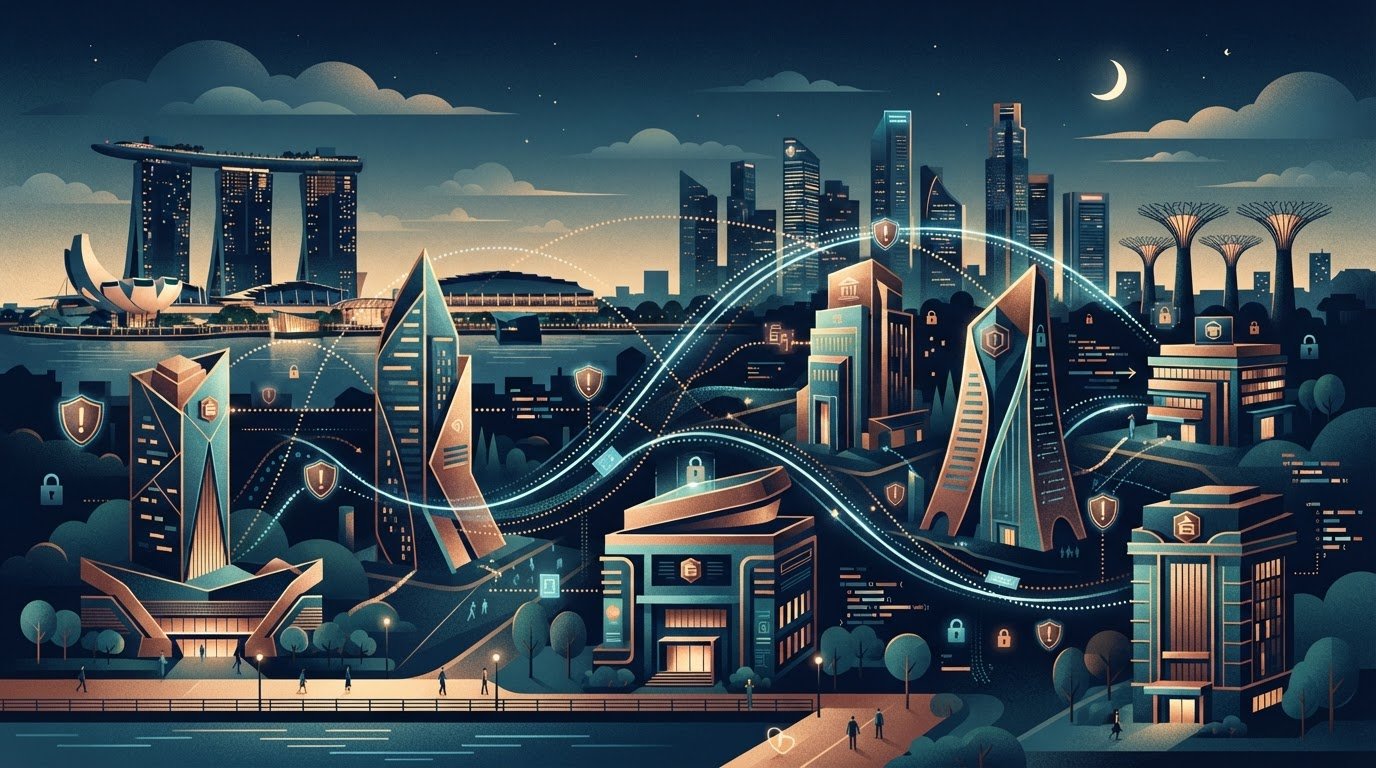
Singapore is exploring a banking-industry system that would use artificial intelligence to identify suspicious payment patterns across several institutions, rather than leaving each bank to examine only its own transactions. The proposed Scam Detection Utility is one of the clearest examples of how AI could be used to address a practical public problem: criminals can move stolen funds through multiple accounts faster than isolated monitoring systems can respond.
Deputy Prime Minister Gan Kim Yong outlined the approach at the Singapore FinTech Festival on 18 November. According to the Monetary Authority of Singapore (MAS), a proof-of-value exercise involving five banks is already under way, with transaction information pooled securely to assess whether models can recognise patterns that would be invisible to an individual institution.
Why a single bank may miss the bigger picture
Imagine a victim transfers money to an account at one bank. The recipient immediately moves some of it to a second bank, which passes it to several further accounts. Each institution might detect only one link in the chain. A system able to analyse relationships across that chain could potentially identify the wider pattern sooner. This is an illustrative scenario, not a description of a specific investigated scam.
MAS says the work initially focuses on accounts and data in Singapore. An industry-wide approach could eventually improve coordination where the speed of a transaction matters more than the ability to investigate it after the money is gone. But recognising suspicious activity is only the first part of prevention: institutions also need lawful procedures for review, intervention and customer communication.
The regulator says a design study will begin in early 2027 to develop the utility’s blueprint, including how it would be governed and operated. That timing is important. The project is not a nationwide system already deployed to every bank customer, and no public announcement establishes a guaranteed rate of fraud prevention.
What the new AI testing environment adds
MAS and the Future of Finance Institute also announced an AI Innovation Arena that will provide realistic synthetic data for researchers and technology providers. This means specially constructed information designed to resemble relevant transaction patterns, rather than simply placing identifiable customer records into an open experiment.
The initial dataset is intended to reflect interbank transaction patterns and scam activity relevant to the five-bank proof-of-value. MAS says it has worked with Singapore’s Government Technology Agency on the dataset. Developers will be able to test whether models can distinguish suspicious networks from ordinary transactions and compare their usefulness.
The difficult part is not just detecting more activity. A tool that raises too many false alarms could disrupt legitimate customers, delay payments and increase work for bank staff. Its performance must therefore be judged by how accurately it identifies risk, how quickly useful action can follow and whether safeguards protect individuals whose transactions are examined.
Why the governance matters as much as the algorithm
Shared intelligence can create shared responsibility questions. Who may access signals? What evidence justifies pausing a transaction? How can a customer dispute an error? And how should institutions handle records when a suspicious pattern is ultimately found to be innocent? The details of the proposed governance model have not yet been settled publicly.
Singapore’s approach brings banks, public agencies, researchers and technology partners into a common problem-solving exercise. That could be more effective than a series of unrelated tools, but testing and oversight remain essential before large-scale use. Cross-border money movements may eventually demand international cooperation; MAS has mentioned such possibilities without presenting them as current operational coverage.
The next milestone is the 2027 design study, followed by decisions about performance standards, accountability and wider deployment. Consumers should see this as a promising effort to improve prevention, not as a substitute for verifying payment requests or reporting suspicious transfers promptly.
Sources and further reading
Sources: MAS: National AI Missions speech, 18 November; MAS and Future of Finance Institute, 18 November; CNA report, 18 November.