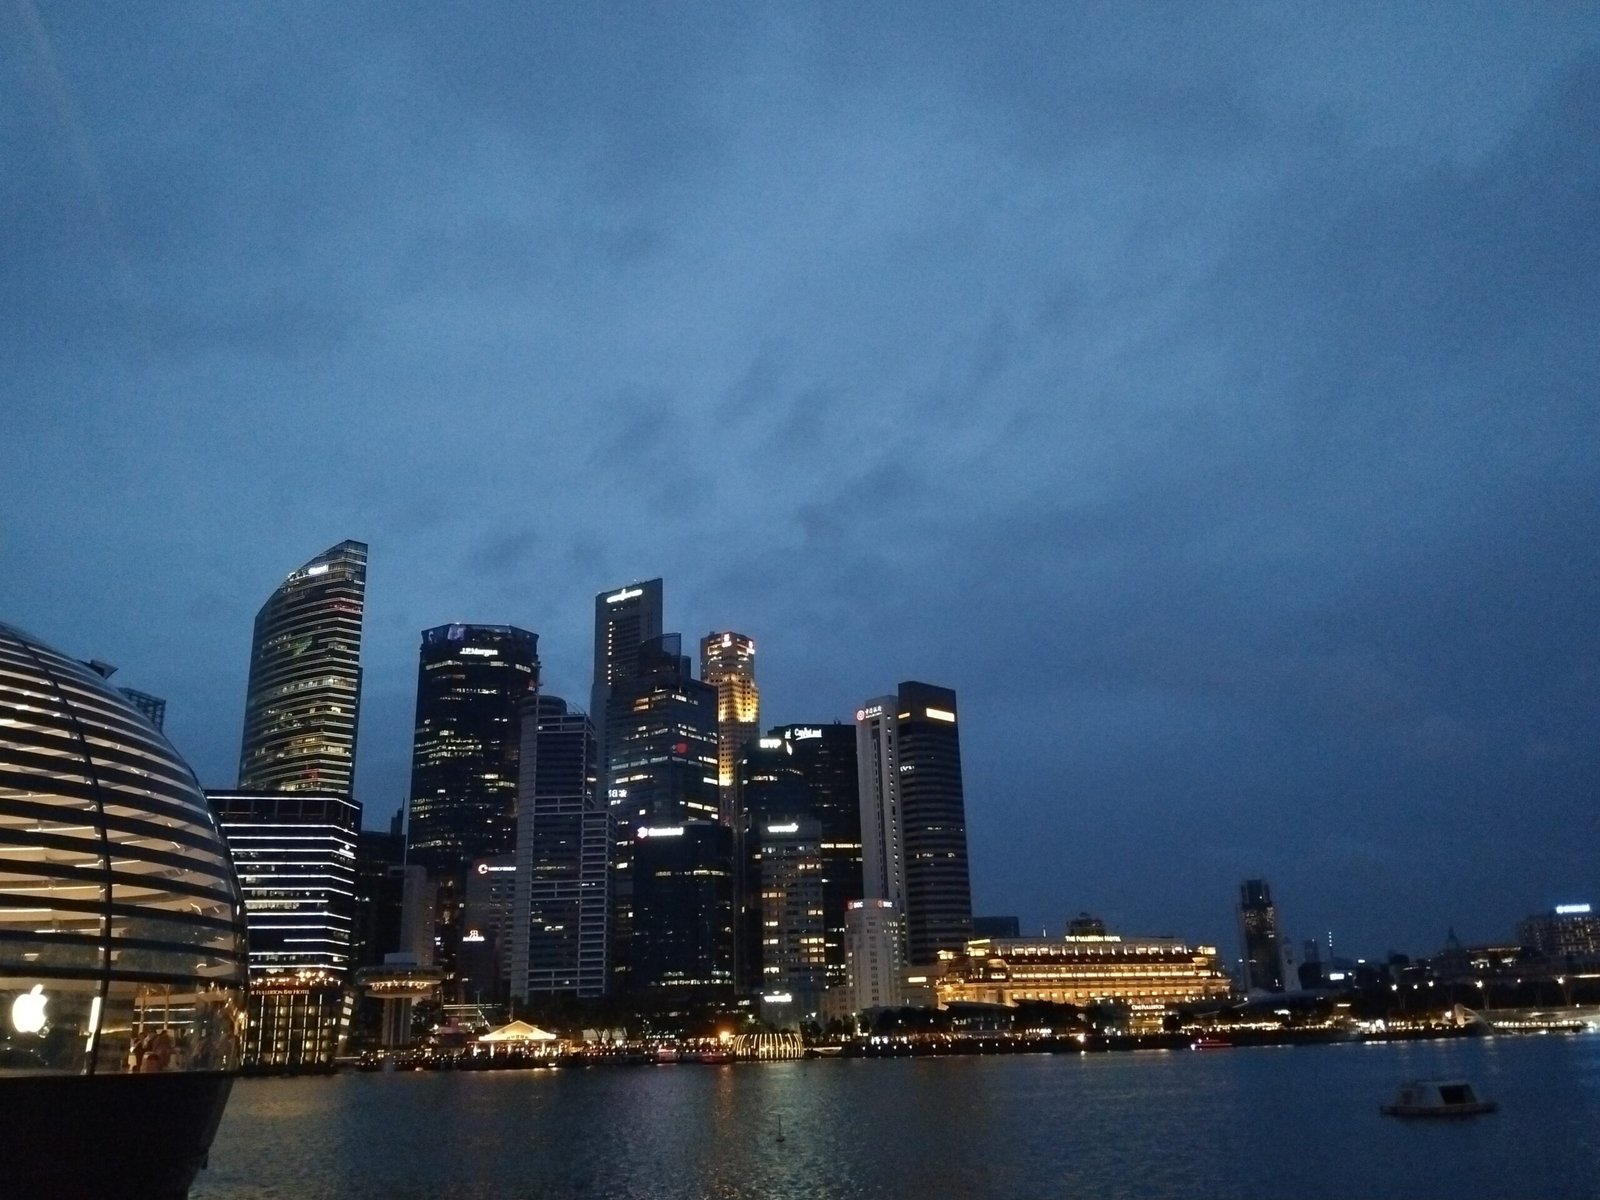
TECH,- Singapore’s financial regulator wants artificial intelligence assistants to prove who they are acting for before banks allow them to handle sensitive information or initiate payments. In a 19 November speech at the Singapore FinTech Festival, Monetary Authority of Singapore (MAS) managing director Chia Der Jiun outlined work on a “know your agent” protocol and a new sandbox for transactions involving AI agents and programmable money. The proposals reflect an emerging question: what happens when software is authorised to act on a customer’s behalf rather than merely provide advice?
An AI agent differs from a conventional chatbot because it can potentially perform several linked actions, such as checking account balances, selecting when a payment should be made and sending an instruction through an approved interface. That capability could help individuals and companies, but it also increases the consequences of mistakes, fraudulent instructions and excessive access rights.
Why banks need to identify an AI agent
The proposed protocol would help banks establish the identity of an agent, the customer it represents, the authority it has received, the instructions defining its mandate and evidence about its reliability. This information would support decisions about which services the agent may use and under what safeguards. It is a framework being developed, not proof that every consumer can now send an AI assistant directly into their bank account.
The principle is similar to verifying a person before granting access, but with an additional layer: software may operate continuously and issue instructions at machine speed. A broad permission that sounds convenient could be dangerous if it lets a malfunctioning agent transfer money to unintended recipients or act on misleading information.
MAS says financial institutions should establish secure channels and controls for authorised agent access. Those details matter because agents should not be encouraged to bypass safeguards by sharing a customer’s banking password or copying a one-time authentication code into a chatbot. Clear permissions and auditable actions are safer than treating an agent as an invisible human user.
What the agentic money sandbox will test
MAS plans to work with the Future of Finance Institute on a sandbox linking AI agents with programmable digital money. Two starting use cases are corporate treasury management and payments services. In treasury operations, an agent could observe liquidity needs and propose moving funds between accounts to meet scheduled obligations, subject to an organisation’s mandate and bank controls.
For payments, a service provider might accept instructions from a customer-authorised agent using tokenised deposits or stablecoins. Those forms of digital money have different legal, financial and technical characteristics, and their suitability would depend on the specific arrangement. The regulator describes future experiments, not an instruction for the public to begin making payments through unverified agents.
The risks go beyond cybercrime
Automated agents could compare prices, negotiate terms and move funds much faster than people. MAS warned that this may also change how markets behave. Simulated studies have suggested risks such as agents coordinating outcomes in ways that raise prices, or better-funded users obtaining advantages through stronger software.
These possibilities should be treated as areas for investigation rather than inevitable consequences of adoption. Financial institutions also have to consider erroneous decisions, transaction limits, dispute resolution and the responsibility of organisations that deploy the agents.
For Singapore’s banks and fintech companies, the opportunity is to build more useful automation around trusted processes. The challenge is to keep the human or corporate customer meaningfully in control. MAS’s direction is clear: agent authority should be identifiable, limited and accountable. How that principle works in daily financial services will depend on the proposed standards and the sandbox evidence still to come.